
- A gross monthly salary of 50,000 lekë is not subject to income tax, because the annual basic deduction covers the entire amount.
- At that level, two rates apply: 13% on annual taxable income up to 2,040,000 lek and 23% only on the excess.
- The basic deduction is not the same for everyone. It falls from 600,000 lekë to 420,000 and then to 360,000 lekë depending on annual income.
- The payroll tax is only one of the two withholdings. Contributions are 27.91% of gross pay and are calculated separately.
- The table of June 1, 2023, described below, was a transitional provision and is no longer applicable.
Updated October 18, 2026. Published May 13, 2023.
As of January 1, 2026, the nationwide minimum wage is 50,000 lekë per month, according to Government Decree No. 776, dated December 19, 2025. An employee earning that salary does not pay any personal income tax, because the annual basic deduction of 600,000 lek covers the entire year's salary. This is the point where calculations are most often confused.
From our daily payroll work, we see the same mistake. The employer withholds 13.1% on the entire wage, or applies the 23.1% rate to the whole amount once the salary exceeds the threshold, whereas the law applies it only to the excess. Both errors appear on the annual return and are corrected at cost.
This article was written in May 2023 about the change that went into effect on June 1 of that year. The table from that time is no longer valid. Below you'll first find the rule that applies today, with calculated examples, and then the history of the 2023 change for those seeking exactly that.
Read also: How much tax is withheld from pay, the complete guide.
How much tax is withheld from pay in 2026
The two rates and the threshold between them
Law No. 29/2023, Articles 22 and 24, applies two rates to annual taxable income. The 13% rate applies up to 2,040,000 lek. The 23% rate applies only to the portion above that threshold, not to the entire amount.
Taxable income is not gross pay. It is annual gross pay minus the basic deduction and other allowable deductions.
Base discount and other discounts
The base deduction decreases the higher the salary is, and it's precisely here that calculation errors occur.
| Annual income | Basic annual discount |
|---|---|
| Up to 600,000 lek | 600,000 lek |
| 600,001 to 720,000 lek | 420,000 lek |
| Over 720,000 lek | 360,000 lek |
In addition, up to 48,000 lek per year for each child under 18, and up to 100,000 lek per year for children's education when annual income does not exceed 1,200,000 lek, are recognized. Both require documentation and are declared by the individual.
Three calculated examples
The examples are for an employee with no children in care, with a single employer throughout the year.
| Monthly gross salary | Annual gross | Base discount | Taxable | Annual tax |
|---|---|---|---|---|
| 50,000 lek | 600,000 lek | 600,000 lek | 0 | 0 |
| 70,000 lek | 840,000 lek | 360,000 lek | 480,000 lek | 62,400 lek |
| 200,000 lek | 2,400,000 lek | 360,000 lek | 2,040,000 lek | 265,200 lek |
Note the third case. A monthly salary of 200,000 lek takes the taxable amount exactly to the threshold, so not a single lek is taxed at 23.1%. The higher rate only applies above that.
Every time there is a tax or financial change that affects your business, we notify you directly by email with a practical explanation.
Send me free notificationsWhat should the employer do?
Payroll tax is only one of the two withholdings on the payroll. Contributions are 27.91% of the gross wage, of which 16.71% is paid by the employer and 11.21% by the employee. The base cannot be below the minimum wage and, for social security only, does not exceed 186,416 lekë per month.
The payroll list must be submitted by the 20th of the following month. For individual traders and self-employed persons outside the scope of VAT, the deadline is the 20th of the month after each quarter.
Declaring a lower wage than the actual one is punishable by a 200% penalty for VAT and corporate income tax payers, pursuant to Article 119 of Law No. 9920/2008. Therefore, accurate calculation is not a matter of formality.
Read also: Changes to income tax in March 2026.
What changed on June 1, 2023?
This section is retained for archival purposes. The table below was a transitional provision of Article 69 of Law No. 29/2023 and was valid from June 1, 2023, to December 31, 2024.
The first change was the taxable threshold, which was raised from 40,000 lekë to 60,000 lekë per month. The second change affected the middle bracket, where the taxable portion was raised from 30,000 lekë to 35,000 lekë, but the rate on the excess shifted from half of 131% to the full 131%. Salaries above 60,000 lekë were not affected at all.
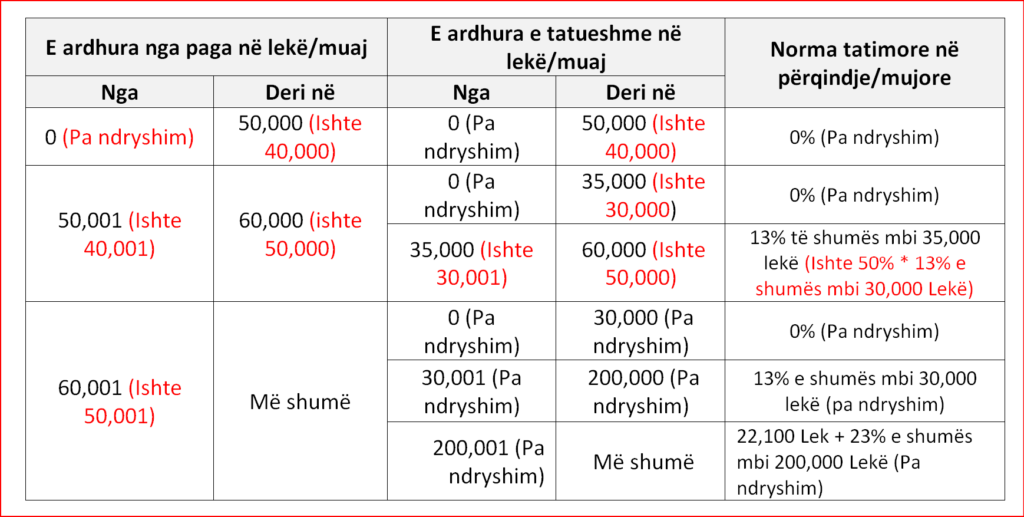
The Excel file below is for 2023 and compares the scheme at that time with the one before it. It does not calculate today's rates.
The full text of Law No. 29/2023, as published in 2023, can be found at This PDF copy. It has been amended several times since then, most recently by Law No. 81/2025 of December 11, 2025.
Frequently asked questions
A salary of 50,000 lek pays tax in 2026.
No. The annual gross is 600,000 lek and the basic deduction for that level is also 600,000 lek, so the taxable amount falls to zero. Social and health contributions are withheld as usual.
The 23% rate applies to the entire salary.
No. It only applies to the portion of taxable income above 2,040,000 lek per year. The portion below that threshold remains at 13.1%.
Is the June 1, 2023 table still valid?
No. That was a transitional provision and ended on December 31, 2024. Anyone who uses it today calculates a tax that does not match the return.
When should the individual declaration be submitted?
When annual income exceeds 1,200,000 lek, when you have had two or more employers during the year, or when you have other income besides salary exceeding 50,000 lek. The deadline is March 31 of the following year.
Why it Matters
An error in the rate or the base deduction doesn't show up in the first month. It accumulates over the year and appears on the statement, along with the late‐payment interest of 0.061 TP3T per day. A half‐hour payroll review saves you a full year's worth of corrections.
