The payroll tax agent is any employer who pays employment income, pursuant to Article 65 of Law No. 29/2023.
There are three obligations: to withhold the tax, to submit the payroll list, and to transfer the tax to the treasury.
The deadline is the 20th of the following month for companies and the 20th of the month following the quarter for self-employed individuals and traders.
The rate is the progressive rate when the employee has signed the personal status declaration, and 15% when the payment is not from an employment relationship.
Failure to withhold tax is punishable by 50% of the amount plus the tax itself, and withholding without filing a return is punishable by 100% of the amount.
Verified on October 11, 2026. Article 65 of Law No. 29/2023 was re-enacted by the amendment of Normative Act No. 7, dated December 14, 2023, and Articles 113, 114, and 117 of Law No. 9920/2008 on sanctions.
The payroll tax agent is the employer, not a separate entity. Any business that pays wages automatically assumes this role, along with the responsibility that comes with it.
The most expensive mistake isn't calculating the tax. It's the deadline. An employer who withholds the tax and fails to report it on time is fined 100% of the amount withheld, effectively paying the tax twice.
This page provides the three obligations with their respective deadlines, the two retention rates, the consequences of error, and a worked example. The full text of Article 65, with the noted amendments, is preserved at the end.
Article 65 of Law No. 29/2023 ranks the three together, and none of them replaces the others.
To withhold the tax on employment income, at the time of payment.
To submit the payroll list, that is, the statement of contributions and payroll taxes.
To transfer the tax held in the budget treasury account.
Failure to file a declaration and filing a declaration without payment are both separate violations, with different consequences. This is explained in the fines section.
Deadlines according to the employer's form.
The deadline does not depend on the number of employees; it depends on the form of the employer.
Employer
Periodicity
Deadline
Entities, that is, commercial companies
Monthly
The 20th of the following month
Self-employed individuals and VAT-registered traders
Three-month period
The 20th of the month following the quarter
Self-employed individuals and traders without VAT
Three-month period
The 20th of the month following the quarter
From this comes the mistake we most often see with individuals. They treat the payroll as a monthly obligation and miss the quarterly deadline, or vice versa—they file every month and pay late.
When 15% is held and when the progressive rate
Article 65 provides two rules, and the choice between them does not depend on the amount of the payment.
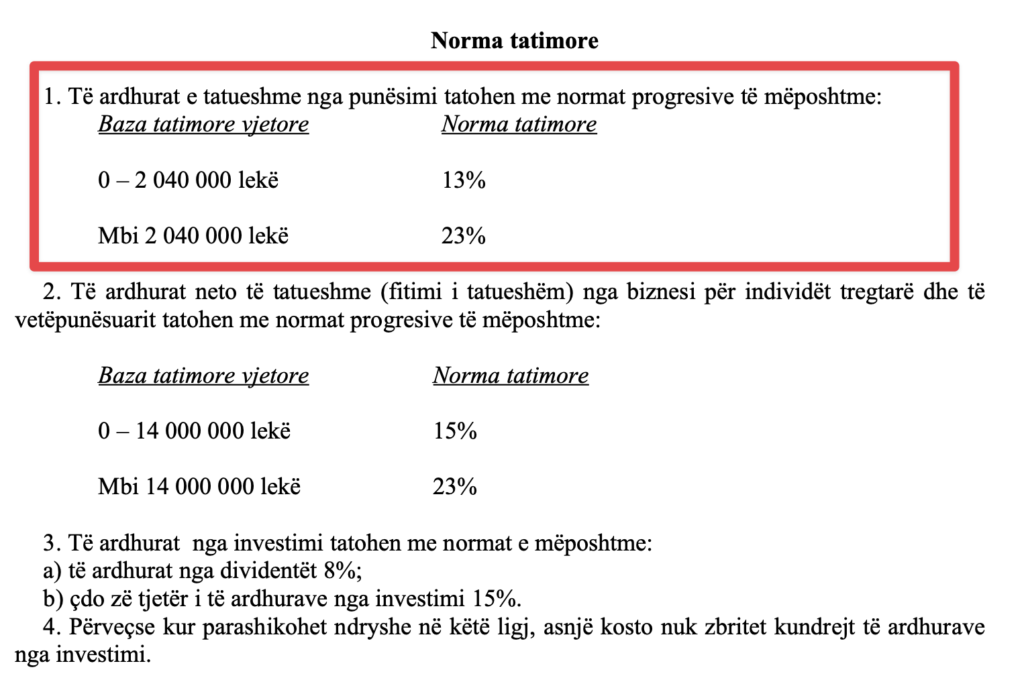
The progressive scale of Article 24 applies when the employee has signed the declaration on personal status with that employer. In other cases, when the payment is not considered to arise from an employment relationship, it is withheld. 15% payment.
When an employee works for multiple employers, only one applies deductions from the tax base. The other employers apply the progressive rate without deductions.
The penalties are not provided by the Income Tax Law but by Law No. 9920/2008 on Tax Procedures. Therefore, many employers cannot find them when they read only Article 65.
Violation
Consequence
Article
It does not withhold tax from the payment.
Fine of 50%, plus the amount of the tax itself.
Article 117
He keeps the tax and doesn't declare it.
Fine in the amount of 100%
Article 117
Fails to file the statement on time.
10,000 lekë for VAT or corporate income tax payers, 5,000 lekë for others, 3,000 lekë for individuals.
Article 113
Did not pay the obligation on time.
Late fee: 0.061% per day
Article 114
General boundary
Fines do not exceed 100% of the obligation; interest is calculated separately.
Article 111, point 5
The same provisions apply to the withholding agent, which is a different role from this one. The distinction and completion of the declaration are provided by Withholding agent.
Calculated example
A trading company withholds 12,000 lek in payroll taxes on March wages. Its deadline is April 20. The table shows how much each road costs.
What's happening?
Calculation
The cost
Declare and pay on time
Tax only
12,000 lek
Declared 10 days late
12,000 fine, plus 10,000 late interest at 0.061 TP3T for 10 days.
22,072 lek
He holds it and doesn't declare it.
12,000 plus fine 100%
24,000 lek
He doesn't remember it at all.
12,000 plus fine 50%
18,000 lek
The third line is the one that surprises. Withholding tax without declaring it costs more than not withholding at all, because the law treats it as if you withheld the full amount for the government.
Every time there is a tax or financial change that affects your business, we notify you directly by email with a practical explanation.
Any employer who is required to withhold income tax from employment. No separate registration or appointment is required. The role arises automatically with the first payroll payment.
Until the payroll is submitted
The 20th of the month following for companies. The 20th of the month following the quarter for self-employed individuals and sole traders, with or without VAT.
What is the fine when the payroll list is not submitted on time?
10,000 lekë for entities registered for VAT or corporate income tax, 5,000 lekë for other entities, and 3,000 lekë for individuals, pursuant to Article 113 of Law No. 9920/2008. Late payment interest is calculated separately.
When 15% is applied instead of the progressive scale.
When the payment is not considered to have arisen from an employment relationship and the employee has not signed the personal status declaration with that employer.
Does anything change when an employee works for two employers?
Yes. Only the employer with whom the declaration has been signed applies deductions to the tax base. Others apply the progressive rate without deductions.
Is it the same as the withholding agent?
No. The payroll agent is regulated by Article 65 and covers wages. The withholding agent is regulated by Article 56 and covers other payments such as rents, dividends, and services. The penalties are the same.
Text of Article 65 with amendments
How is it read?. The part of outlined It's the old formulation that no longer applies. The part of underlined This is the new wording, pursuant to Normative Act No. 7 of December 14, 2023, published in the Official Gazette No. 182 of December 16, 2023.
1. Any employer who is obligated to pay income from employment is required to withhold tax on this income, to submit the payroll list and transfer the tax withheld on the payroll list to the budget treasury account no later than the 20th of the following month for entities and no later than the 20th day of the month following each quarter for self-employed individuals or sole proprietors. and self-employed individuals or traders registered for VAT, and no later than the 20th of the month following each quarter for self-employed individuals or traders who are not registered for VAT.
(Amended by Normative Act No. 7, dated December 14, 2023, published in the Official Gazette) No. 182, December 16, 2023
The payroll tax agent is required to withhold tax in accordance with this provision:
a) the progressive rate of taxation under Article 24 of this law if the personal income taxpayer signs the declaration of personal status with this employer, pursuant to Article 64 of this law;
“…Article" 24
b) 15% of the payment in other cases not covered by paragraph (a) of this point and not considered income from employment relationships.
Monthly deductions from the tax base
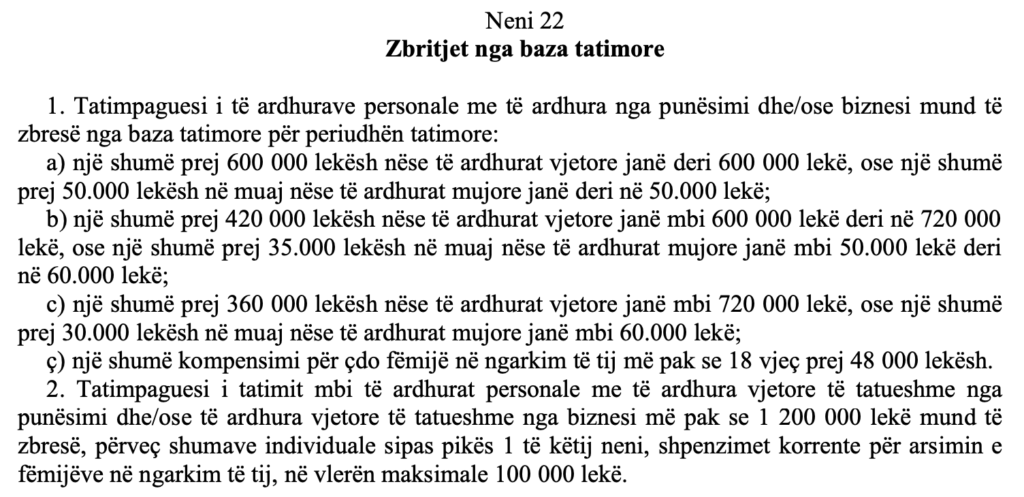
The payroll tax agent is required to take into account, on a monthly basis, one-twelfth of the deductions from the tax base, in accordance with letters “a,” “b,” and “c” of paragraph 1 of Baby 22 of this law, and the deductions from the tax base under Article 20 of this law when calculating the income tax on the payroll for an employee who has signed the personal status declaration with this payroll tax agent. If the employee is also employed by other employers, those other employers, in their capacity as payroll agents, will apply the progressive rate of taxation under Article 24 of this law and will not apply the deductions from the tax base under Baby 22, point 1, letters “a”, “b” and “c” of this law.
“… Article 22
2. Deductions and offsets under points 1, letter “ç”, and 2 of Baby 22 and according to Article 23 Under this law, they may only be claimed by personal income taxpayers on the annual tax return.
4. Payroll tax agents are responsible for paying employment income taxes with the same responsibility as if they were their own tax liability.
Employer's obligations for records
3. Every employer must keep records of the income paid and the tax withheld and submit the payroll in accordance with the provisions of the tax legislation and the legislation on social security and health insurance contributions, as well as the instructions issued by the minister responsible for finance for the implementation of these laws. The form, content, deadlines, and procedures for submitting the payroll register are determined in the secondary regulations of the minister responsible for finance, issued for the implementation of the tax legislation, including this law, as well as the legislation on social security and health insurance contributions.
The General Directorate of Taxes' explanation of the payroll, in video.
The payroll deadline isn't the same for a corporation and for an individual, and the error only shows up when the fine is issued. We keep each client's calendar and file it on the correct day.
Andi Haxhillari is an economist and the founder of AlProfit Consult, an accounting, tax advisory, and financial management firm in Tirana, established in 2015. He holds the professional title of Certified Accountant, certificate no. 359, issued by the Certification Authority of the Ministry of Finance on July 4, 2012. He graduated with a Master's degree in Accounting and as a General Economist from the Faculty of Economics at the University of Tirana. For more than ten years, he has worked as an external economist for small and medium-sized businesses in Albania.